For automotive financiers, customer retention has traditionally been treated as an end-of-contract activity: identify customers approaching maturity, send a communication and hope the dealer follows up.
That model is increasingly inadequate.
Customer circumstances change throughout the finance term. Vehicle equity moves, new models enter the market, usage patterns evolve and loyalty can weaken long before a contract reaches its final months.
Retention is therefore not a single campaign. It is an ongoing commercial discipline.
Instead of waiting for a customer to approach contract maturity, financiers have an opportunity to identify relevant moments throughout the ownership journey and create a reason for the customer to engage.
This requires a shift from asking:
“Which customers are coming to maturity?”
to:
“Which customers have a reason to engage with us now?”
A customer can become relevant for a new conversation at many different points in the ownership lifecycle.
It may be positive vehicle equity, a guaranteed future value milestone, changing vehicle requirements, a warranty event, servicing activity, a new model launch or a compelling finance proposition.
These signals do not all occur at the same time.
A mature retention model therefore needs to monitor the customer lifecycle continuously, identify when there is a credible reason to engage and provide the dealer with a clear, timely action.
This is where data becomes commercially valuable.
Rather than simply producing a list of customers approaching maturity, financiers can use available customer, vehicle and finance information to prioritise opportunities based on relevance and timing.
Solutions such as GFV & Retention Solutions can help connect these signals to practical retention activity, creating a more structured approach to managing the future customer pipeline.
The objective is not simply to generate more leads.
It is to identify the right customer, at the right time, with the right reason to engage.
Automotive financiers occupy a particularly valuable position within the ownership ecosystem.
They often hold a detailed view of the finance contract, maturity position, vehicle information and customer relationship. OEMs understand product cycles, brand strategy and model launches, while dealers manage the customer relationship and ultimately deliver the retail experience.
No single participant can maximise retention in isolation.
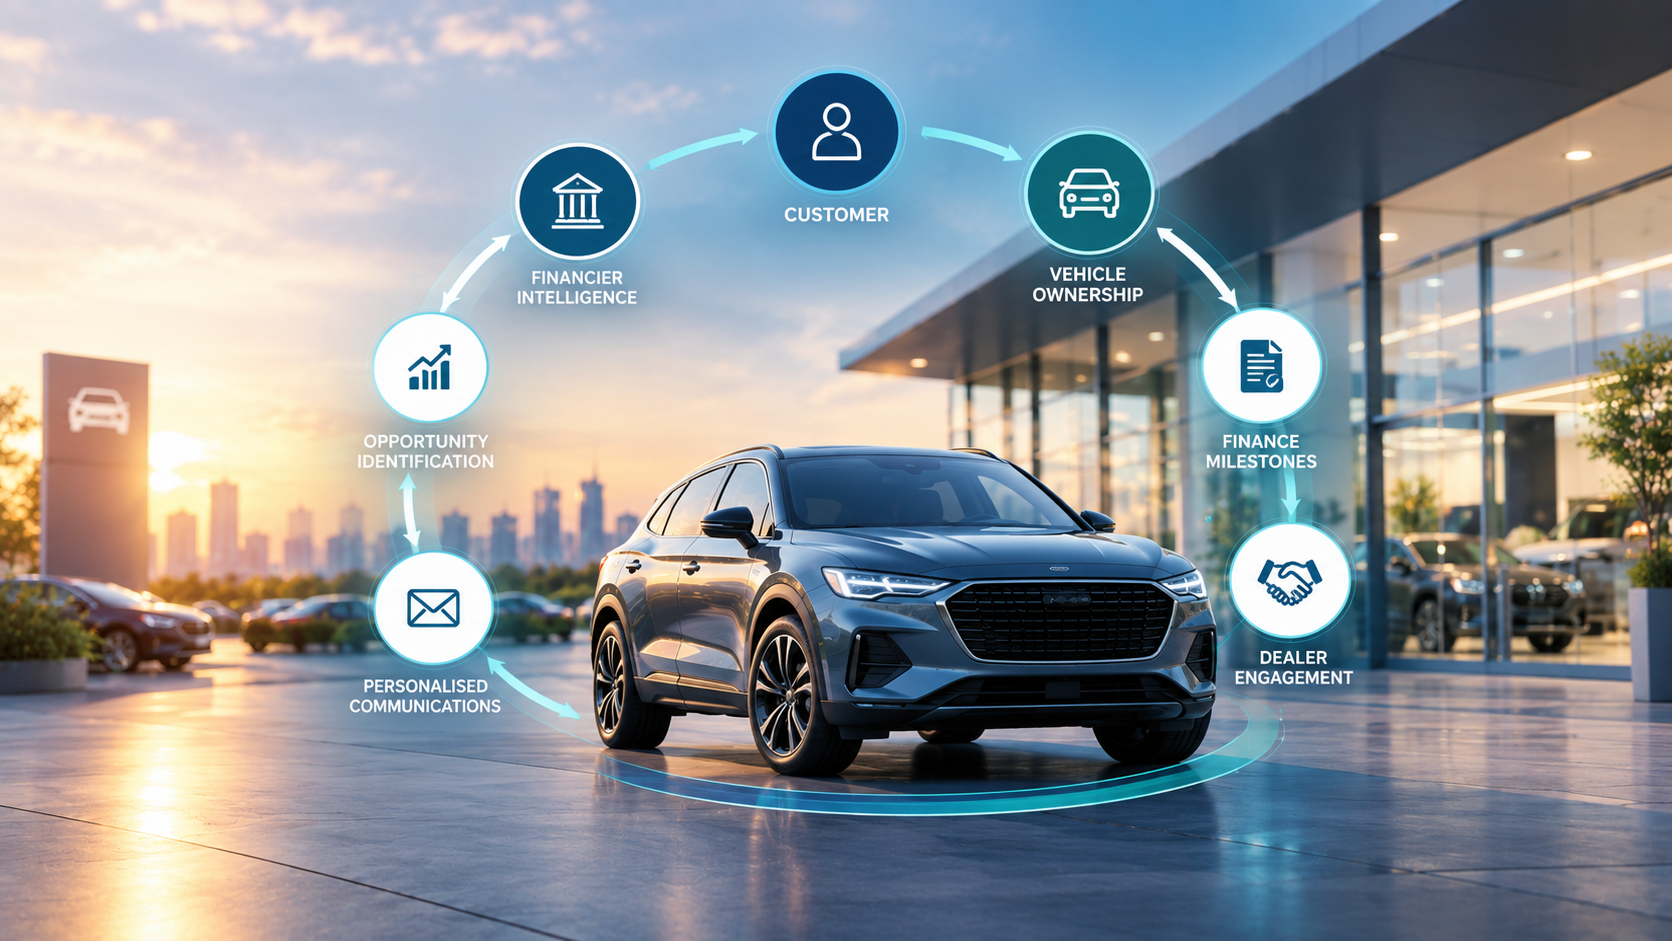
The financier can therefore act as a coordinating intelligence layer between these participants: identifying opportunities, enabling relevant offers, supporting dealer action and measuring what happens next.
This creates a connected retention model.
Instead of:
Financier → Lead List → Dealer → Customer
the process becomes:
Customer Data → Opportunity Identification → Prioritisation → Dealer Action → Customer Engagement → Commercial Outcome
That distinction matters.
It moves retention away from being a marketing activity and towards becoming a measurable commercial capability.
For automotive financiers looking to strengthen this approach, Op2ma’s solutions for financiers bring together finance intelligence, dealer performance and customer lifecycle opportunities to support more informed action.
One of the biggest changes required is the way retention performance is measured.
Emails sent, calls attempted and leads allocated are useful operational metrics. But they do not necessarily tell a financier whether the customer stayed with the brand, renewed their finance or purchased another vehicle.
Retention reporting should go further.
A more complete view can include:
This creates a clearer connection between activity and commercial outcome.
A retention programme should ultimately answer questions such as:
Did the customer engage?
Did the dealer act?
Did the customer enter the next stage of the buying journey?
Was another vehicle sold?
Was finance renewed?
Did the customer remain with the brand or move elsewhere?
Without this visibility, retention can easily become a reporting exercise rather than a performance discipline.
The strongest retention programmes are not built around a single annual campaign.
They combine integrated data, prioritised opportunities, relevant communications, dealer workflow and transparent reporting to create a repeatable operating rhythm.
That means continuously identifying customers who may have a reason to engage rather than waiting until the final months of a finance contract.
It also means giving dealers more than a customer list.
Dealers need to understand why the customer is being contacted, what opportunity exists and what action should happen next.
When intelligence, workflow and measurement are connected, retention becomes easier to manage and more meaningful to the customer.
The result is a model where the financier can continuously identify opportunities, the dealer can act on them and the organisation can measure what happened.
For OEMs and branded financiers, this can create a stronger connection between the finance portfolio, dealer network and future vehicle pipeline.
Ri-gnr8 is designed around this type of connected approach, helping financiers work with finance-book data, GFV opportunities, customer segments and dealer networks to create more actionable retention opportunities.
The future of finance retention is not about sending more communications.
It is about creating better reasons to have a conversation.
A customer approaching maturity may be an obvious opportunity, but they are not the only opportunity.
Positive equity, changing circumstances, vehicle lifecycle events, product launches and finance milestones can all create moments where a relevant conversation becomes commercially valuable.
The role of the financier is to recognise those moments and help the dealer act on them.
This is where connected data and performance intelligence can make a difference.
Instead of treating the finance book as a static database, it becomes a continuously evolving source of commercial opportunities.
And instead of treating retention as a campaign that starts and ends, it becomes part of the way the business operates.
Treat retention as a connected operating capability across the finance and ownership lifecycle—not a list distributed near contract maturity.
The opportunity for automotive financiers is to move beyond end-of-contract activity and build a retention model that continuously identifies customer opportunities, enables dealer action and measures the commercial outcome.
When finance intelligence, customer insight and dealer execution work together, retention becomes more measurable, more relevant to customers and more valuable across the automotive ecosystem.
Talk to Ann Cawkwell at Op2ma on +61 419 854 970.